Design Highlights
- Regularly review your policy for exclusions and limitations to avoid surprises during a claim.
- Document property conditions and maintenance activities to support your claims effectively.
- Understand the difference between flood damage and storm-related water damage to ensure adequate coverage.
- Consider investing in flood detection systems to mitigate financial risks from unexpected leaks.
- Be aware that water-related claims can significantly increase your premiums; manage your claims wisely.
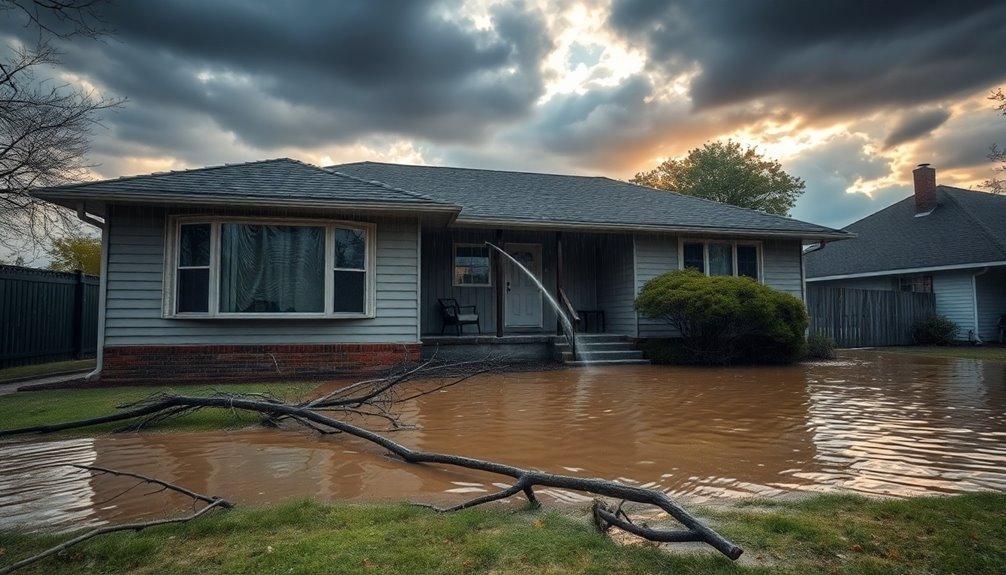
When it comes to water and storm damage insurance, many homeowners are in for a rude awakening. You think you’re covered? Think again. Most standard homeowners and renters policies exclude flood damage outright. That’s right—if water rises from the streets or rivers overflow, you might as well be looking for a lifeboat. You’ll need specialized coverage from the National Flood Insurance Program.
And don’t even get started on the fine print. The distinction between flood damage and storm-related water damage is like the difference between a rock and a hard place. Good luck interpreting that.
The fine print is a minefield; distinguishing flood damage from storm-related water damage is no easy feat. Good luck!
Wind-driven damage might seem like a different ballgame. Falling trees or wind pushing rain through broken windows? Sure, that could trigger coverage under typical home policies. But the devil is in the details. You might think you’re golden if a sudden storm causes a pipe to burst. Nope, insurers love to argue about “faulty construction.” Water damage from sewer backups may or may not be covered, depending on your policy wording, adding another layer of complexity.
So if you’re counting on them to honor your claim after cashing those premium checks, you might want to double-check your policy wording.
Sewer backups are another landmine. Most policies exclude that nasty mess entirely. Can you imagine thousands of dollars in damages with no coverage? Some providers might offer sewer backup endorsements, but good luck finding them. It’s like looking for a needle in a haystack.
If you think your home’s plumbing is invincible, think again. Gradual leaks? Forget it. Those slow, sneaky leaks are your problem, not the insurer’s. Maintenance issues? They love that phrase.
And appliances? Well, if your washing machine suddenly breaks, you may get lucky. But if it’s just wear and tear, you’re out of luck. It’s like they want you to document every little thing. “Oh, the leak was sudden? Prove it!” Suddenly, you’re a detective in your own home. Keep in mind that replacement cost coverage pays the full value of damaged belongings, while actual cash value factors in depreciation—a critical distinction when filing a claim.
Let’s talk money. Water-related claims can jack up premiums by 19-25%. Yes, you read that right. And if you make a second claim in three years? Good luck keeping coverage.
Deductibles range from $1,000 to $2,500. Want to avoid that? Invest in a flood detection system—it’s cheaper than your deductible.
In the end, maneuvering through water and storm damage insurance is like walking through a minefield. One wrong step, and you’re financially devastated. So, homeowners, stay alert. The insurance game is a tricky one.